Calculators / Home Affordability Calculator
Home Affordability Calculator
See what home price fits your income, debts and down payment. Build your budget before you shop, then get pre-approved in one day.
Left for housing at a 43% ratio
Yes. Is Closer Than You Think.
Happy with your budget? Get pre-approved in one day. Your loan officer compares rates from 100+ lenders and brings you the strongest offer your file qualifies for.
★★★★★ 500+ reviews
NMLS #1955132
Homeowners helped
Five-star reviews
Loans funded
States licensed
Know Your Budget Before You Shop
Every result updates as you change a number. The payment and ratio below use the $9,000 income example.
The price range your numbers support.
The payment that budget creates, taxes and insurance included.
Your monthly debts, including the new payment, compared with your gross income. Lenders use it to size your loan.
Home budget minus your down payment.
Your down payment in dollars and as a percentage.
How We Find Your Budget
We start with your income, subtract your debts and turn what is left into a payment and a home price.
Your rate, term, taxes and insurance turn that payment into a home price.
Gross Monthly Income
Your income before taxes. Self-employed? Qualifying income can differ from gross receipts. We'll help you find the right figure.
Monthly Debts
Car loans, student loans and credit card minimums. Utilities and groceries stay out.
Down Payment
More down buys more home at the same payment.
Interest Rate
A lower rate buys more home. We find your best rate across 100+ lenders.
See Your Budget in Action
Earning $9,000 a month with $600 in monthly debts? Load it, then change any number.
| Item | Example |
|---|---|
| Gross monthly income | $9,000 |
| Monthly debts | $600 |
| Example total-debt ratio | 43% |
| Total monthly debt allowed | $3,870 |
| Left for housing | $3,270 |
What Raises or Lowers Your Budget
Higher qualifying income raises your budget.
Every debt dollar comes out of your housing room.
More down shrinks the loan at the same price.
A lower rate buys a higher price.
They vary by county and use up part of your payment.
FHA, VA and conventional loans use different assumptions.
The questions buyers ask most
Straight answers to what buyers search before they talk to a lender.
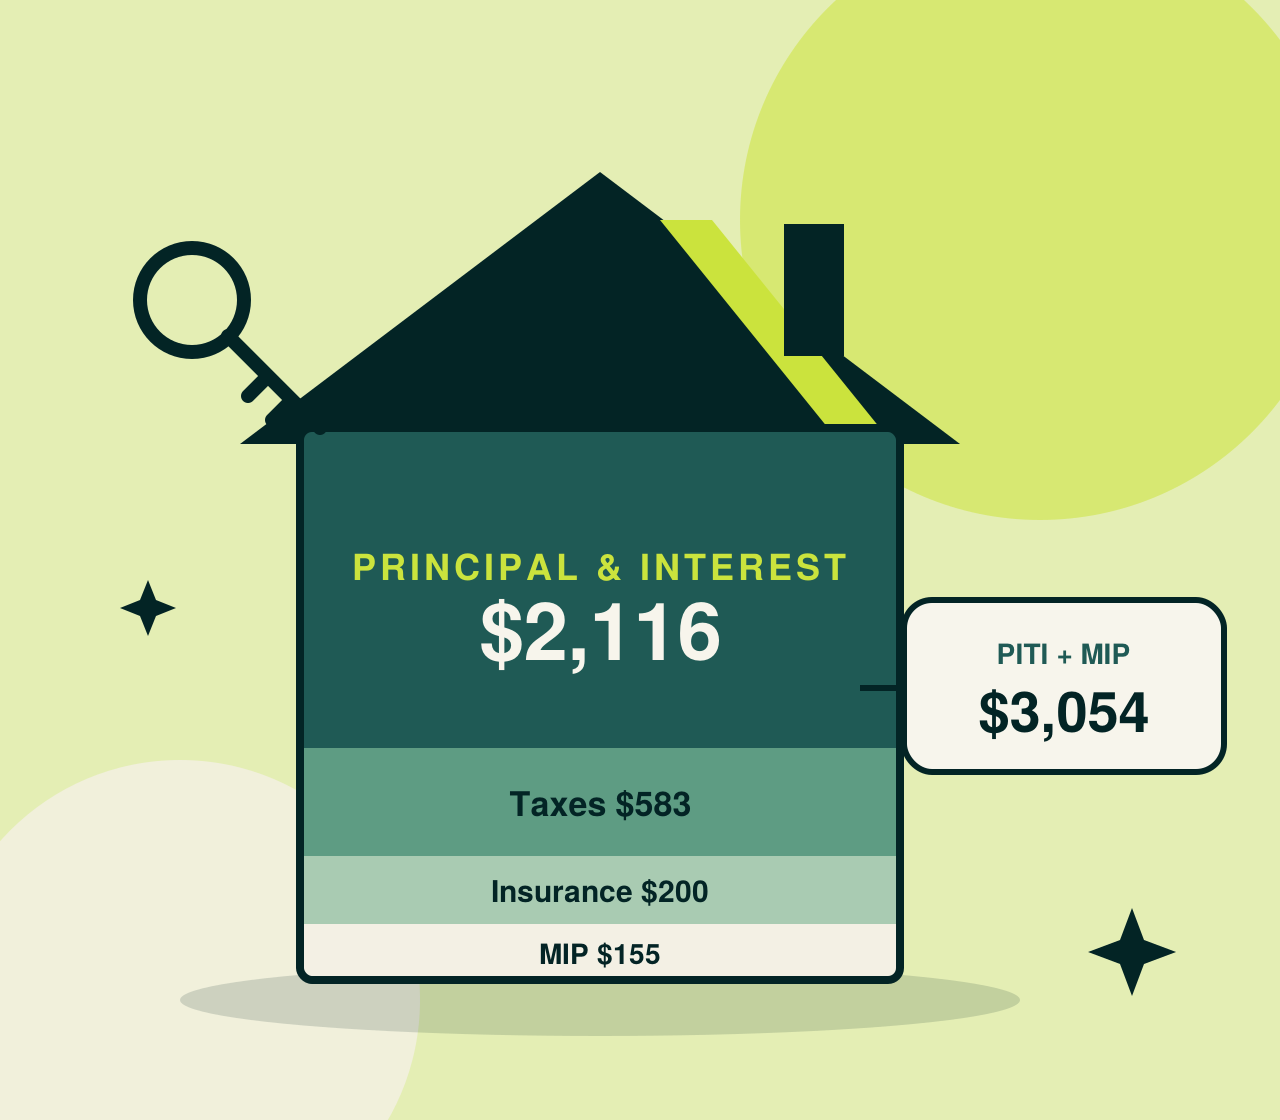
How Much House Can I Afford?
It depends on your income, debts, down payment and rate. We'll run your numbers against real program guidelines and show you your price range.
How Should I Budget Before House Hunting?
Pick a monthly payment you are comfortable with first. Then work back to a price. Save for closing costs on top of your down payment.
How Does DTI Affect What I Can Afford?
Lower debts mean a bigger budget. Paying off a card or car loan before you apply can raise the price you qualify for.
How Income Changes Your Housing Budget
Same $600 in monthly debts, five income levels, a 43% example ratio.
| Gross monthly income | Total debt allowed (43%) | Left for housing after $600 debts |
|---|---|---|
| $6,000 | $2,580 | $1,980 |
| $8,000 | $3,440 | $2,840 |
| $10,000 | $4,300 | $3,700 |
| $12,000 | $5,160 | $4,560 |
| $15,000 | $6,450 | $5,850 |
The 43% ratio is an illustration and does not determine eligibility. Limits vary by loan program and lender.
Home Affordability Calculator FAQs
Quick answers to the questions buyers ask most about what they can afford.
Have a question? Ask us.
Our loan officers will walk you through your numbers, no pressure and no obligation.
★★★★★ 500+ five-star reviews
How much house can I afford on my income?
Enter your numbers above. We’ll confirm the result with your documents and show you your real range.
What income do I need to buy a home?
There is no single number. Lenders compare your debts, including the new payment, with your gross monthly income. We’ll show you what fits.
What is DTI?
Debt-to-income is your monthly debts divided by your gross monthly income. Lenders use it to judge how comfortably you can handle a mortgage.
Does self-employed income count differently?
Yes. Lenders often average your income after business expenses. We’ll help you document it.
Should I budget for more than the payment?
Yes. Plan for closing costs, moving costs, repairs and a cash reserve.
Is a calculator the same as pre-approval?
A calculator gives an estimate. Pre-approval checks your income, credit and assets. We can pre-approve you in one day.
Keep Planning Your Purchase
Run the Numbers.
Find Your Yes.
Estimate payments, see your costs and compare your options with every Austin Capital Mortgage calculator.
This calculator provides estimates for informational purposes only. It is not a loan offer, pre-approval or commitment to lend. Actual rates, payments, mortgage insurance and eligibility depend on credit, income, property and program guidelines. Equal Housing Lender.
This is an estimate. Qualifying income for self-employed borrowers can differ from gross receipts.
Equal Housing Opportunity · Austin Capital Mortgage, a brand of Aspire Home Loans, LLC, NMLS #1955132. The Earned Equity Program is offered through a correspondent relationship with Arrive Home™ LLC.
For informational purposes only; not a commitment to lend, an offer of credit, or legal or tax advice. A buyer does not hold title to the home at origination; title transfers upon payoff or refinance.
Qualification is subject to underwriting approval; program terms and availability are subject to change. Not available in Alaska or New York.
Contact
Copyright © 2026 Austin Capital Mortgage