Calculators / Down Payment Calculator
Down Payment Calculator
Compare down payments side by side. See your loan, your payment and your cash needed, then get pre-approved in one day.
$400,000 HOME · 3.5% DOWN$14,000
Cash down on a $400,000 home
NEXT STEP
Yes. Is Closer Than You Think.
Found a down payment that works? Get pre-approved in one day. Your loan officer compares rates from 100+ lenders and brings you the strongest offer your file qualifies for.
★★★★★ 500+ reviews
NMLS #1955132
20K+
Homeowners helped
500+
Five-star reviews
$7B+
Loans funded
26
States licensed
See What Your Down Payment Does
Change the price or the amount down. Every number updates. The cards below use the $400,000 example further down this page.
DOWN PAYMENT$14,000
Your cash toward the purchase, in dollars and percent.
Starting loan amount
$386,000Home price minus down payment, before any financed fees.
Monthly payment
$2,440Principal and interest, plus the taxes and insurance you enter.
Loan-to-value
96.5%Your loan as a share of the home price. Lower often means better pricing and less mortgage insurance.
Mortgage insurance
VariesUnder 20% down? Expect a monthly mortgage insurance cost. The size depends on the program.
Cash down vs cash to close
Plus costsYour down payment is one piece. Closing costs and prepaids come on top.
How We Compare Your Options
We subtract your down payment from the price, then run your payment on the loan.
THE FORMULALoan amount = Home price − Down paymentMonthly P&I = L × r ÷ (1 − (1 + r)−n)
L = loan amount, r = annual rate ÷ 12, n = number of months.
01
Home Price
The price you and the seller agree on.
02
Down Payment ($)
Enter dollars and we show the percentage.
03
Down Payment (%)
Enter a percentage and we show the dollars. Minimums depend on the program.
04
Interest Rate
Lenders often price lower loan-to-value loans better. We find your best rate across 100+ lenders.
05
Loan Term
Shorter terms raise your payment and cut interest.
06
Property Taxes
Estimated yearly taxes, split into monthly escrow.
07
Homeowners Insurance
Your yearly premium divided by 12.
See Your Down Payment in Numbers
Buying a $400,000 home with 3.5% down? Load it, then try 5%, 10% and 20%.
| Item | Example |
|---|---|
| Home price | $400,000 |
| Down payment (3.5%) | $14,000 |
| Starting loan amount | $386,000 |
| Loan term | 30 years |
| Interest rate | 6.5% (example only) |
| Principal and interest | about $2,440 a month |
What Changes Your Down Payment Math
Home Price
A bigger price means a bigger check for every percent.
Loan Program
Minimums differ. FHA starts at 3.5% down with a 580+ credit score.
Mortgage Insurance
More down can lower or remove it.
Interest Rate
A bigger down payment can earn a better rate.
Closing Costs
They come on top of your down payment.
Assistance and Gifts
Allowed sources depend on the program. We'll confirm what applies.
The questions buyers ask most
Straight answers to what buyers search before they talk to a lender.
3% vs 20%≈$430/mo
DOWN PAYMENT LEVELS
3% vs 5% vs 20% Down: What Changes?
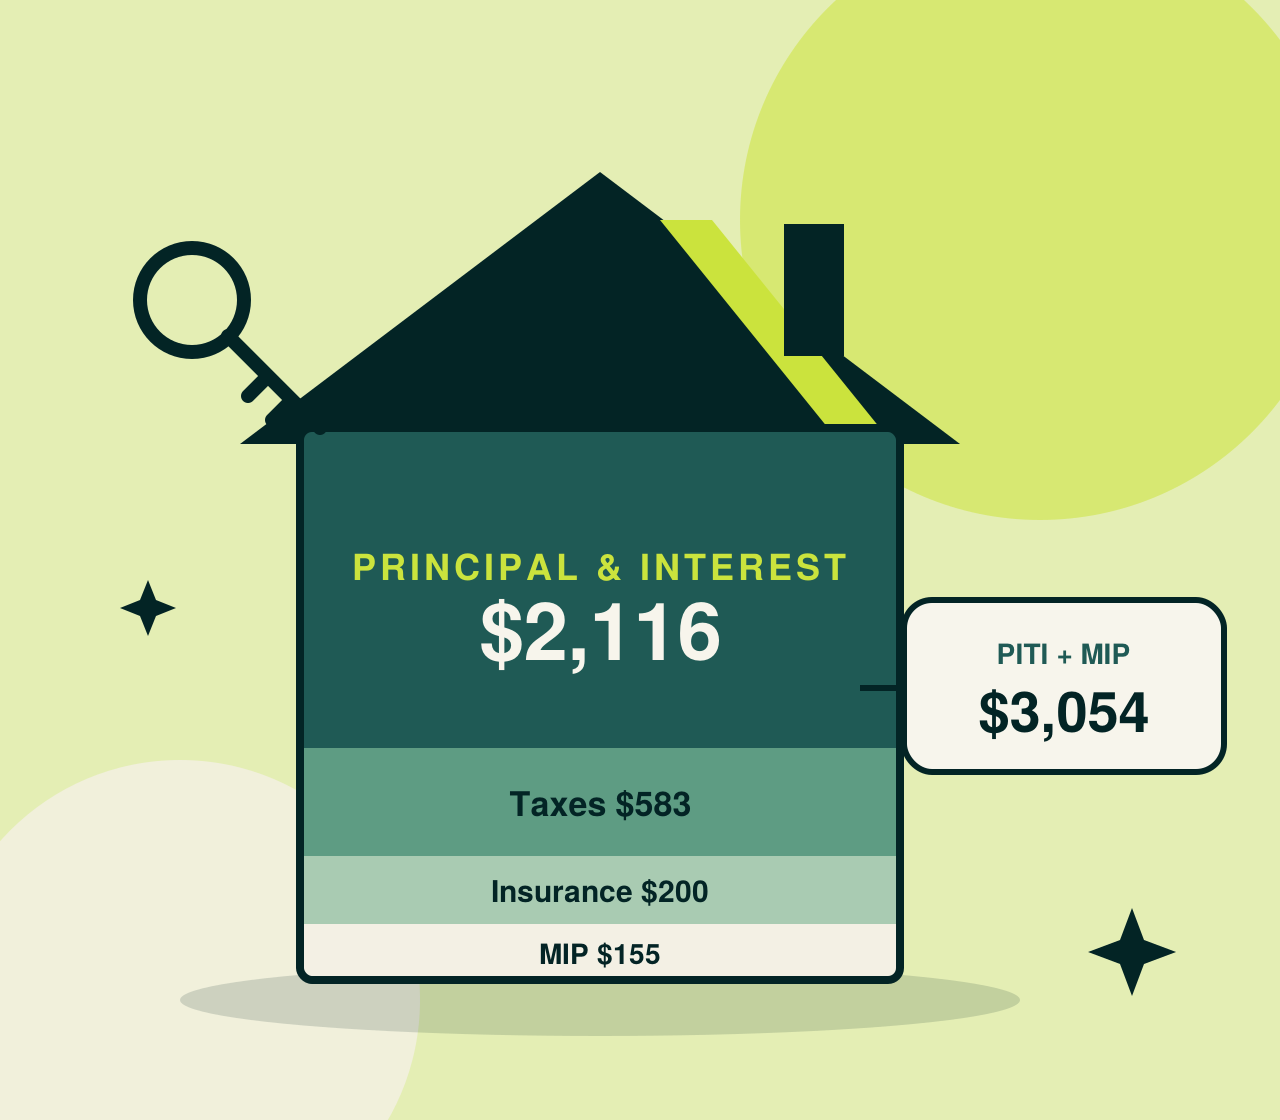
More down means a smaller loan, a lower payment and often less mortgage insurance. On a $400,000 home, 3% down vs 20% down is a gap of about $430 a month.
- 3% down: $12,000 cash, about $2,452 a month
- 5% down: $20,000 cash, about $2,402 a month
- 20% down: $80,000 cash, about $2,023 a month
- Principal and interest at 6.5% over 30 years
CASH YOU NEED
Down Payment vs Cash to Close
Your down payment is one part of the cash you need. Closing costs and prepaid taxes and insurance come on top. We'll give you a full estimate before you commit.
| Cash at closing | What it covers |
|---|---|
| Down payment | Your share of the price. It lowers your loan. |
| Closing costs | Lender, title, appraisal and other services. |
| Prepaids | Upfront property taxes, homeowners insurance and interest. |
MINIMUM DOWN
How Much Do I Need to Put Down?
FHA starts at 3.5% down. Some conventional programs start at 3% down. We compare 100+ lenders to match your savings and credit.
FHA3.5% down
With a 580+ credit score
CONVENTIONAL3% down
Some programs start here
How Down Payments Change a $400,000 Home
Putting more down means less to borrow and more cash out of pocket. Pick what fits your savings and goals.
| Down payment | Cash down | Starting loan amount | Principal and interest (6.5%, 30 years) |
|---|---|---|---|
| 3% | $12,000 | $388,000 | $2,452 |
| 3.5%FHA MINIMUM | $14,000 | $386,000 | $2,440 |
| 5% | $20,000 | $380,000 | $2,402 |
| 10% | $40,000 | $360,000 | $2,275 |
| 20% | $80,000 | $320,000 | $2,023 |
Examples are for illustration and do not determine eligibility. 3% down options are conventional programs. FHA requires at least 3.5% down. Loan amounts are shown before any financed mortgage insurance fees.
Down Payment Calculator FAQs
Quick answers to the questions buyers ask most about down payments.
Have a question? Ask us.
Our loan officers will walk you through your numbers, no pressure and no obligation.
★★★★★ 500+ five-star reviews
How much should I put down on a house?
Put down what fits your savings and still leaves cash in reserve. We’ll show you the payment at each level.
Do I need 20% down?
No. Many programs accept far less. Under 20% usually adds mortgage insurance. We’ll show you the trade-off.
What is the difference between down payment and closing costs?
Your down payment lowers your loan. Closing costs pay for the lender, title, appraisal and other services. You need cash for both.
Where can my down payment come from?
Depending on the program: savings, gifts or assistance. Your loan officer confirms what applies.
Does more down lower mortgage insurance?
Often yes. A bigger down payment shrinks the loan the insurance is based on. Some programs drop it at higher levels. We’ll confirm for your loan.
Is a calculator the same as pre-approval?
A calculator gives an estimate. Pre-approval checks your income, credit and assets. We can pre-approve you in one day.
Keep Planning Your Purchase
Run the Numbers.
Find Your Yes.
Estimate payments, see your costs and compare your options with every Austin Capital Mortgage calculator.
Loan amount$380,000
5% down30 yr
Rate (example)6.5%
$3,202/mo
P&I $2,402Taxes $600
This calculator provides estimates for informational purposes only. It is not a loan offer, pre-approval or commitment to lend. Actual rates, payments, mortgage insurance and eligibility depend on credit, income, property and program guidelines. Equal Housing Lender.
Down payment is not total cash to close.
Equal Housing Opportunity · Austin Capital Mortgage, a brand of Aspire Home Loans, LLC, NMLS #1955132. The Earned Equity Program is offered through a correspondent relationship with Arrive Home™ LLC.
For informational purposes only; not a commitment to lend, an offer of credit, or legal or tax advice. A buyer does not hold title to the home at origination; title transfers upon payoff or refinance.
Qualification is subject to underwriting approval; program terms and availability are subject to change. Not available in Alaska or New York.
Contact
Copyright © 2026 Austin Capital Mortgage