Buy a Home without SSN
New to the U.S.? Qualify with just 3 months of bank statements and a credit score as low as 580 and no-score options.
- No prepayment penalty or forced exit
- Keep 100% of your home's appreciation
- Low Down Payment, Low Credit Score
★★★★★ 500+ five-star reviews · Trusted by 20K+ homeowners · Google · Zillow · Yelp
EARNED EQUITY PROGRAMITIN · DACA · H-1BNo tax returns needed
Austin Capital Mortgage
You got approved!
You got approved!
20K+Homeowners helped
500+Five-star reviews
$7B+Loans funded
10-21Average days to close
Is the Earned Equity
Program Right for You?
Many people who can afford a home still hear “no” from a bank. If a lender told you no, the problem may have been their checklist, not your finances. See if any of these sound like you.
Not sure? One short, confidential conversation with a loan officer can answer your questions. No obligation.
ITIN holders
You work, pay taxes and build your life here using an Individual Taxpayer Identification Number.
- No Social Security number required
- Qualify with bank statements
DACA recipients
You’ve grown up here, you work here, and you’re ready to put down roots.
H-1B visa holders
You’ve built your career here and you’re ready to stop renting.
Self-employed & business owners
Your write-offs lower your taxable income, but your bank deposits show what you really earn.
1099 & gig workers
You have a non-traditional income source that doesn’t come with a W-2.
Turned down by a bank
You can comfortably afford the payment, but an automated approval system said no.
Are You Eligible for the
Earned Equity Program?
Here's what we look for.
Credit score
580+ to start, or 500 with 3 months’ reserves.
Down payment
A low down payment to get started.
Income documentation
Qualify on 3 months of bank statements, with no tax returns needed. Other documents may be requested depending on how you earn your income.
Housing history
A documented record of your rent payments can help you qualify. Ask us what counts.
Availability
Not available in Alaska or New York.
No tax returns needed3 months of statements
Credit Score 580+Or 500 with 3 months' reserves
“I’m an ITIN holder and I’m looking to buy my first home.”
Talk to a Loan Officer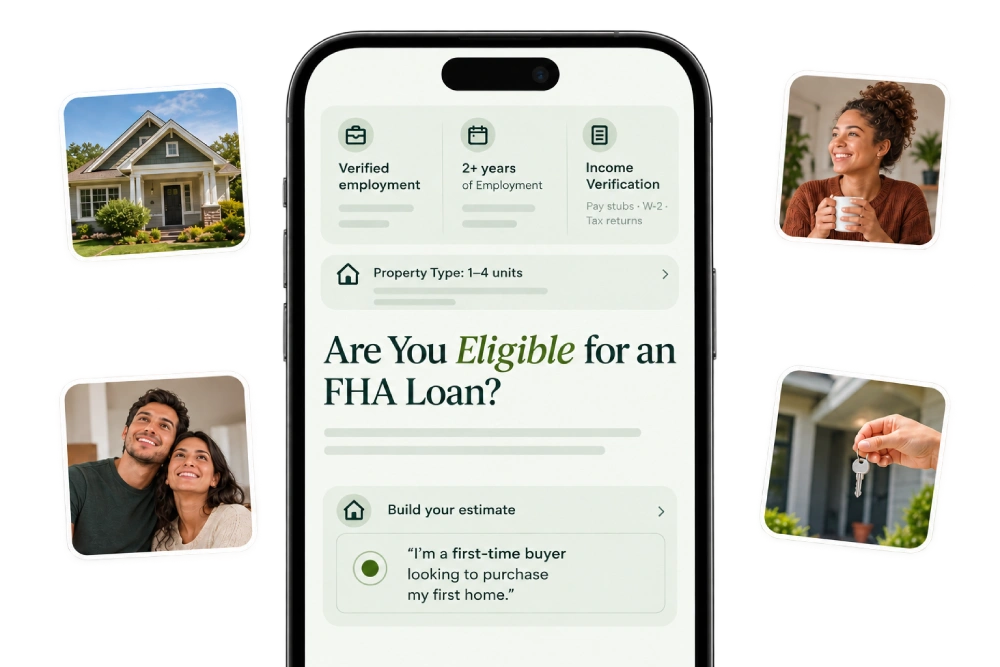
Here's your next stepYour estimate is readyView payment options →
What Our Homeowners Say
How It Works (Step-by-step)
A dedicated loan officer will walk you through the whole process from the very first call, all the way to the closing.
01
01
Confidential consultation
Tell a loan officer your goals and ask anything. It’s private, with no obligation.
02
02
Share your documents
Start with 3 months of bank statements. We’ll tell you exactly what else, if anything, your situation needs.
03
03
Get pre-approved
In many cases, you’ll have a pre-approval the next day.
04
04
Find your home
Tour homes with your agent and make an offer with confidence.
05
05
Close & move in
A partner entity holds title to the home while you live in it and make your payments.
06
06
Take full ownership
When you’re ready and qualify, you buy the home outright or refinance, and title transfers fully into your name.
How Ana & Luis Bought Their Home Without SSN
ITIN · 610 credit score
3 months of bank statements
“We pay our rent on time every month.”
We just never had the paperwork a bank wanted.
The problem
They're ITIN holders with steady deposits, but business write-offs lower the income on their tax returns, and a bank's automated system said no.
ITIN
Identification
610
Credit score
3 months
Bank statements
Goals
- Stop renting within the year
- Keep 100% of their home's appreciation
- A clear path to putting the home in their name
What ACM did
- Qualified them on 3 months of bank statements, with no tax returns
- Walked them through how title works before they committed
- Mapped out their options for taking full ownership later
The path ahead
- Pre-approved the next day
- At closing, a partner entity holds title
- Later, refinance or assume once they qualify
Your Path to Full Homeownership
There's no prepayment penalty and no balloon payment. When you're ready, choose the path that fits.
Assume the FHA loan
Take over the loan in your own name, if you meet FHA guidelines at that time.
Refinance
Refinance into your own mortgage, and title transfers fully into your name.
Keep paying
Stay in your home, keep making your payments and keep building toward ownership.
Sell
Once the home is in your name, you can sell it and keep 100% of the appreciation.
EEP vs Other
Loan Options
Other loan options may also work for you. A loan officer
can help you find the right one in one call.
| Feature | EEP | Conventional | FHA | ITIN loan (non-QM) |
|---|---|---|---|---|
| ITIN holders | Eligible | Generally requires an SSN | Generally requires an SSN | Eligible |
| DACA recipients | Eligible | Case by case | Not eligible for new FHA loans since May 2025 | Varies by lender |
| H-1B visa holders | Eligible | Often eligible | Not eligible for new FHA loans since May 2025 | Varies by lender |
| Title at closing | Partner entity | You | You | You |
| Appreciation | 100% yours | 100% yours | 100% yours | 100% yours |
Guidelines shown are general and can vary by lender and program. Talk to a loan officer for your specific options.
Why Choose Austin Capital Mortgage
Local experts, fast closings and clear communication from application to keys.
01 Reviews
500+ five-star reviews
Homeowners rate us five stars on Google, Zillow and Yelp.
02 Closings

On-time closings
Clear timelines and regular updates keep your closing on track.
03 Experts
Local loan experts
Loan officers in 26 states who know your local market.
04 Pricing
Transparent pricing
Clear rates and fees upfront, with no surprises at the table.
How Does Ownership Work Here?
This isn’t a traditional mortgage, and we want you to fully understand it before you decide.
At closing, a partner entity holds title to the home, not you, while you live in it and make your payments under a long-term homeownership agreement.
What stays the same for you:
- You keep 100% of any increase in your home's value the whole time.
- No prepayment penalty, no balloon payment and no forced exit.
When does the home go into my name?
Title transfers fully into your name when you assume the loan, buy the home outright or refinance, as long as you qualify at that time.
Until then, the home isn’t legally yours to sell.
Have questions? Ask your loan officer as many questions as you need to, that’s what we’re here for.
Next step
Start with a confidential conversation.
- No commitment to proceed
- Talk directly with a licensed loan officer
- Find out which path fits your situation
Check Your Eligibility in 2 Minutes
Fill out this form to check if you're eligible for the EEP Program.
Meet Your Earned Equity Program Experts
Real people who answer the phone and walk you through every step, from your first question to the keys.

Charlie Cooper
President
Charlie Cooper
NMLS: 326203Charlie leads Austin Capital Mortgage and brings a long-term view of the lending business to every file. A University of Houston finance graduate, he's known for getting to the right answer quickly.
Book an Appointment
Jett Middleton
Loan Officer
Jett Middleton
NMLS: 2736777Jett focuses on first-time homebuyers and down payment assistance programs, along with DSCR loans for investors.
Book an Appointment
Tom Oltmann
Loan Officer
Tom Oltmann
NMLS: 308768Tom has originated loans at ACM since 2008, after more than a decade managing retail stores for AT&T. He works with first-time buyers and investors and keeps clients informed at each step.
Book an Appointment
Adrienne Sanchez
Loan Officer
Adrienne Sanchez
NMLS: 1213046Adrienne entered the mortgage industry in 1994, led operations at a mortgage company and joined ACM in 2009. She brings three decades of lending experience to every file.
Book an Appointment
Clint Brinkoeter
Loan Officer
Clint Brinkoeter
NMLS: 2592637Clint has more than a decade of experience in mortgage origination. A Texas State finance graduate, he's known for his market knowledge and close community ties.
Book an Appointment
Lance Kotal
Loan Originator
Lance Kotal
NMLS: 308707Lance has been a loan officer in Austin since 2001. A UT Austin economics graduate who helped his father build houses, he brings hands-on knowledge of homes to the financing conversation.
Book an AppointmentEarned Equity Program FAQs
Clear answers about how the program works.
Still have questions?
Talk to a local mortgage expert. You'll get straight answers with no pressure.
Can I buy a home with an ITIN?
Yes. ITIN holders can qualify for the Earned Equity Program.
Can DACA recipients qualify?
Yes. DACA recipients can qualify.
I'm on an H-1B visa. Can I buy a home?
Yes. H-1B visa holders can qualify. We’ll confirm which work authorization documents we need from you.
Do I need tax returns?
No. You can qualify on 3 months of bank statements. Depending on your income, we may ask for a few other documents.
What credit score do I need?
As low as 580, or 500 with 3 months’ reserves.
Who holds title to the home?
A partner entity holds title at closing. Title transfers fully to you when you assume the loan, buy the home outright or refinance.
Can I sell the home?
Yes, once the home is in your name. Until then, a partner entity holds title.
Do I keep my home's appreciation?
Yes. You keep 100% of any increase in your home’s value.
Is there a prepayment penalty or balloon payment?
No. There’s no prepayment penalty, no balloon and no forced exit.