A P&L mortgage lets a self-employed borrower qualify using a profit and loss statement instead of, or alongside, tax returns. Lenders still average income over time, still subtract business write-offs from what counts, and still apply stricter rules for negative years or a business under two years old.
Most edge cases come down to how consistent, verifiable, and profitable the P&L looks to an underwriter. If your income looks inconsistent on paper, the fix usually starts with reviewing exactly how your P&L converts into qualifying income before you apply.
Self-employed income rarely lines up cleanly with what a mortgage application asks for. A profit and loss statement, often shortened to P&L, is a financial statement that shows a business’s revenue, expenses, and net profit over a set period.
The questions below walk through the edge cases that come up most often once a self-employed borrower’s P&L doesn’t look like a tidy, steady paycheck.
What Counts as Income on a P&L Mortgage?
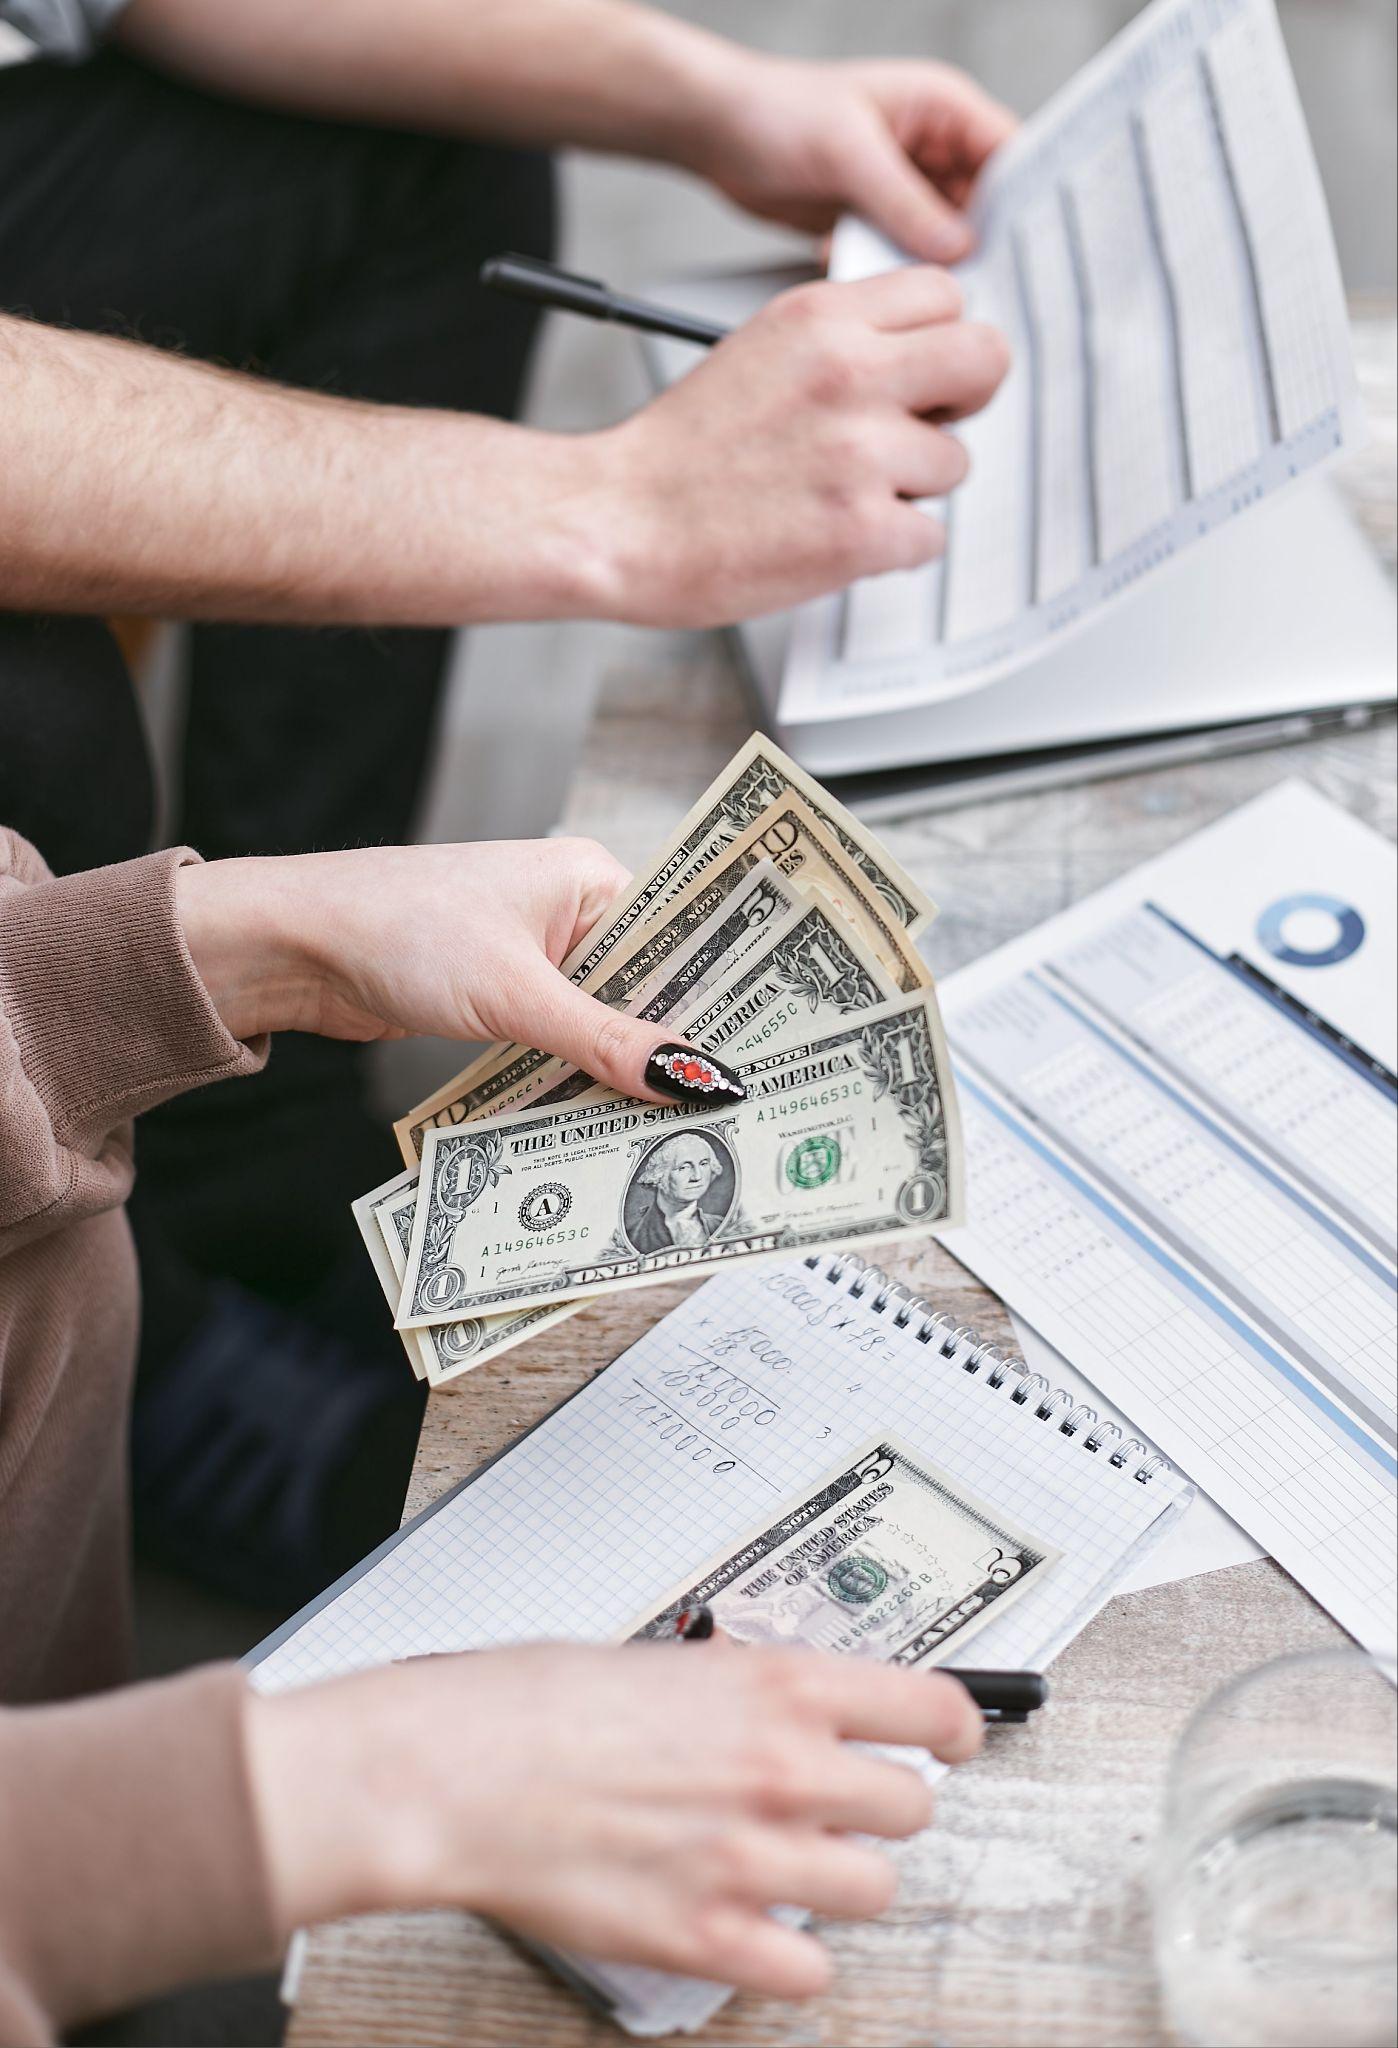
Lenders count net profit, not gross revenue, as qualifying income on a P&L mortgage. Net profit is what remains after the business’s operating expenses, cost of goods sold, and deductions are subtracted from total revenue. A borrower who brought in a large amount of revenue but spent most of it running the business will qualify on the smaller number that is left over.
This is the single biggest source of confusion for self-employed borrowers moving from a W-2 mindset to a self-employed one. A paycheck shows one number. A P&L shows revenue, then a list of subtractions, then a final number, and it’s that final number a lender is trained to review first.
- Revenue: total money the business brought in
- Operating expenses: rent, payroll, software, supplies, and similar recurring costs
- Net profit: what’s left after expenses, and generally the starting point for qualifying income
How Do Write-Offs Affect What a Lender Counts?
Write-offs reduce net profit, and net profit is what a lender counts, so aggressive write-offs directly lower qualifying income even when the business is healthy. A borrower who writes off a large share of revenue to reduce tax liability will see that same reduction show up on the P&L a lender reviews.
This is why a business that looks profitable in daily operations can still show modest qualifying income on paper. Some expenses, like depreciation or certain one-time costs, may be added back under specific loan programs if properly documented, but this varies by lender and program and is not automatic.
A borrower expecting a heavy write-off year to fully “wash out” on a mortgage application is usually surprised by how much it reduces the number an underwriter uses.
Can You Qualify With a Negative Year or a Recent Business Slowdown?
A negative year does not automatically disqualify a P&L mortgage applicant, but it does trigger closer underwriting review and often requires a documented explanation. Lenders want to understand whether the decline was a one-time event, such as losing a major client or a temporary market disruption, or a sign of an ongoing downward trend.
Underwriters generally look for evidence that the business has since stabilized or recovered. That can include a rebound shown in the most recent months of P&L data, new client contracts, or a letter of explanation describing what changed and why it isn’t expected to recur.
A single soft year followed by a documented recovery is treated very differently from two consecutive declining years.
- A one-time dip with a clear cause and documented recovery is more workable
- A multi-year downward trend raises more scrutiny and may limit program options
- Supporting documentation, such as new contracts or a CPA letter, strengthens a negative-year file
How Do Lenders Average Inconsistent P&L Income?
Lenders typically average qualifying income across the documentation period, most often 12 to 24 months of P&L data, rather than using a single strong month or quarter. This protects against a borrower cherry-picking their best period, but it also means a few unusually strong months can be diluted by slower ones in the same window.
For a borrower with genuinely seasonal or project-based income, this averaging can understate their typical earning power. Providing a longer income history, year-over-year comparisons, or documentation showing a consistent seasonal pattern can help an underwriter see the full picture instead of judging one slow stretch in isolation.
“The borrowers who struggle most with a P&L mortgage aren’t the ones with lower income. They’re the ones who don’t understand yet how averaging and write-offs interact until they see the qualifying number in writing.”
— Charlie Cooper, President, Austin Capital Mortgage
Can You Get a P&L Mortgage With Less Than Two Years in Business?
Most P&L mortgage programs are built around a two-year self-employment history, though some non-QM programs will consider a business with as little as one year of documented history under stricter conditions.
Debt-to-income ratio, or DTI, which measures how much of a borrower’s monthly income goes toward debt payments, and other underwriting factors typically need to be stronger to offset the shorter track record. This documentation requirement traces back to federal ability-to-repay rules, which require lenders to verify income, assets, and debts before extending a mortgage.
A newer business without two years of history isn’t automatically excluded, but it usually needs a stronger overall file: higher reserves, lower DTI, or a related professional background that supports the business’s viability. This is very program-specific, so what one lender allows for a one-year business may not be available everywhere. Learn more about 1099 income mortgages.
How Is a P&L Mortgage Different From a Bank Statement Loan?
A P&L mortgage uses a formal profit and loss statement, often with a CPA-prepared or reviewed document, while a bank statement loan calculates income from deposit activity across personal or business bank statements.
Both are non-traditional documentation, or non-QM, paths built for self-employed borrowers, but they start from different source documents and can produce different qualifying income numbers for the same business.
| Feature | P&L Mortgage | Bank Statement Loan |
|---|---|---|
| Primary document | Profit and loss statement (often CPA-prepared) | 12 to 24 months of bank statements |
| Income basis | Net profit after expenses | Deposits, with an expense factor applied |
| Best fit for | Businesses with clean, well-documented bookkeeping | Borrowers whose bank deposits reflect income more clearly than their P&L |
| Write-off impact | Directly reduces qualifying income | Less directly tied to tax write-offs |
| Documentation source | Accounting records | Bank account activity |
A borrower with heavy legitimate write-offs but strong cash flow through their accounts sometimes qualifies for more under a bank statement loan than a P&L mortgage, and the reverse is also true depending on how the business is run. Reviewing both calculations before choosing a program is usually worth the extra step. Read about bank statement loans.
Knowing Your Net, Not Just Your Revenue
A self-employed graphic designer brought in $250,000 in business revenue over the prior year but had written off $120,000 in legitimate business expenses, from software subscriptions to a home office deduction and contractor payments.
On paper, that left roughly $130,000 in net profit for the year, and that net profit figure, not the $250,000 in revenue, became the starting point for the lender’s income calculation.
Because the P&L was CPA-prepared and the expense categories were well documented, the underwriter was able to average the net profit across the two-year history without additional scrutiny.
The borrower initially expected to qualify based on total revenue and was surprised by the lower number, but understanding the calculation early allowed the loan officer to structure the file around the correct figure from the start rather than running into a mismatch later in underwriting.
On a P&L mortgage, lenders qualify borrowers on net profit after write-offs, not total business revenue, so borrowers should calculate their likely qualifying income before assuming their revenue number will carry the application. Gain a deeper understanding of the P&L-only process.
How to Prepare for a P&L Mortgage
- Pull your business’s P&L for the last 12 to 24 months and identify the net profit line, not just revenue
- List any large or unusual write-offs from the past two years and be ready to explain them
- If you had a negative or declining year, gather documentation explaining the cause and any recovery since
- Confirm how long your business has been operating and whether that meets a two-year history or requires a shorter-history program
- Ask a loan officer to run your numbers under both a P&L mortgage and a bank statement loan for comparison
Ready to see where your numbers land? A loan officer can review your specific P&L and walk through what actually counts before you apply.
Your Situation Is More Common Than You Think. Let’s Review It.
Every self-employed file looks a little different once write-offs, seasonality, or a slow year enter the picture. Austin Capital Mortgage has been reviewing self-employed income scenarios since 1996 and works with 100+ lenders across conventional, government, and non-QM programs, so an edge case in one program’s guidelines often has a workable path in another.
Austin Capital Mortgage works with 100+ lenders, a hybrid banker and broker model, which means more program access and more flexibility to find the path that fits the borrower’s actual file.