Buy with Little to Zero Down Payment
Planning to buy a home? With our down payment assistance programs, you don't need a down payment saved up. See your assistance amount before you start house hunting.
- Credit score starting at 600
- No income limits on FHA options
- No first-time-buyer rule
- Forgivable after 36 payments
30+ years lending · 500+ reviews · Licensed in 26 states
ASSISTANCE3.5% or 5% assistanceFHA second lien · 600+ credit
Austin Capital Mortgage
Your pre-approval checklist is ready
Your pre-approval checklist is ready
30+Years lending, since 1996
500+Reviews
26States licensed
100+Lenders compared
Down Payment Doesn't Have to Delay
Your Move
You can have steady income and a strong payment history and still fall short on cash for the down payment. Assistance programs add a second loan or grant to your purchase, so less of your own savings goes toward it. We'll show you which options your file can use.
Not sure? A loan officer can compare your assistance options in one call.
Get a Rate QuotePut as little as 3.5% down with FHA and a second-lien DPA
The assistance covers 3.5% or 5% of the lower of the sales price or appraised value, depending on the option. It comes as a separate second loan alongside your FHA first mortgage.
We’ll show you the amount, the payment (if any) and the rules before you commit.
Texas buyers can combine state DPA with FHA, VA, USDA or HFA conventional
Texas state programs offer assistance of 2%, 3%, 4% or 5% of the loan amount with an FHA, VA, USDA or HFA conventional first mortgage. Income and purchase price limits apply and vary by county.
We’ll check your county limits and tell you whether you fit.
No first-time buyer status needed for many DPA options
The FHA second-lien options and the Texas non-bond DPA do not require first-time buyer status. The Texas bond option and the mortgage credit certificate do.
We’ll tell you which one applies to your situation.
Self-employed buyers can qualify with the right program
Your loan officer reviews how you document your income and matches it to an eligible first mortgage.
We find your best rate and the assistance option that fits your file.
Teachers, veterans, first responders and other public servants may get extra Texas benefits
The Homes for Texas Heroes program carries a higher income limit than Home Sweet Texas for eligible public service workers.
We’ll confirm your occupation qualifies.
Family can co-sign without living in the home
Some DPA options allow a non-occupant family co-borrower under FHA rules, and that co-borrower must be on title.
We’ll check whether this works with your program.
What You Need to Qualify for Down Payment Assistance
Requirements depend on which assistance program and first mortgage you use. The list below shows the main conditions for the two program types on this page.
600+ credit score for FHA second-lien DPA
Most FHA second-lien options require a 600 minimum score on files approved by automated underwriting. Manual underwriting typically needs 660 and a maximum 45% debt-to-income ratio.
We’ll pull your scenario and tell you where you stand.
620+ credit score for Texas state DPA
Texas state programs require a 620 minimum score on government loans and 640 on HFA conventional loans. A 0.25% charge applies at 620 to 639.
We’ll show you the cost with your quote.
Debt-to-income per automated underwriting approval
FHA second-lien options use the automated approval for your debt-to-income ratio, and the second-lien payment counts in the ratio when the loan is repayable.
We’ll calculate your payment with both loans before you decide.
One occupying borrower and the home as your primary residence
The home must be your primary residence. The FHA options cover 1 to 2 unit homes, single-family homes, PUDs, townhomes and approved condos. Texas programs also allow certain 2 to 4 unit homes when you live in one unit.
Homebuyer education before closing
At least one borrower completes a short education course before closing. Fannie Mae’s HomeView course is free for the FHA options.
We’ll send you the right link when you reach that step.
Income limits apply to Texas state programs
Texas programs set income and purchase price limits by county and household size. Limits change each year, so we’ll check the current numbers for your county.
The FHA second-lien options carry no area median income limit.
Requirements may vary by lender and loan scenario. Meeting the minimums does not guarantee approval.
Verified employment · Stable income2+ years of Employment
Income VerificationPay stubs · W-2 · Tax returns
Get Your Personalized Quote in 2 Minutes
Fill our 2 min form to see live rates from lenders based on your scenario. One application, 100+ lenders.
Get Free Rate Quote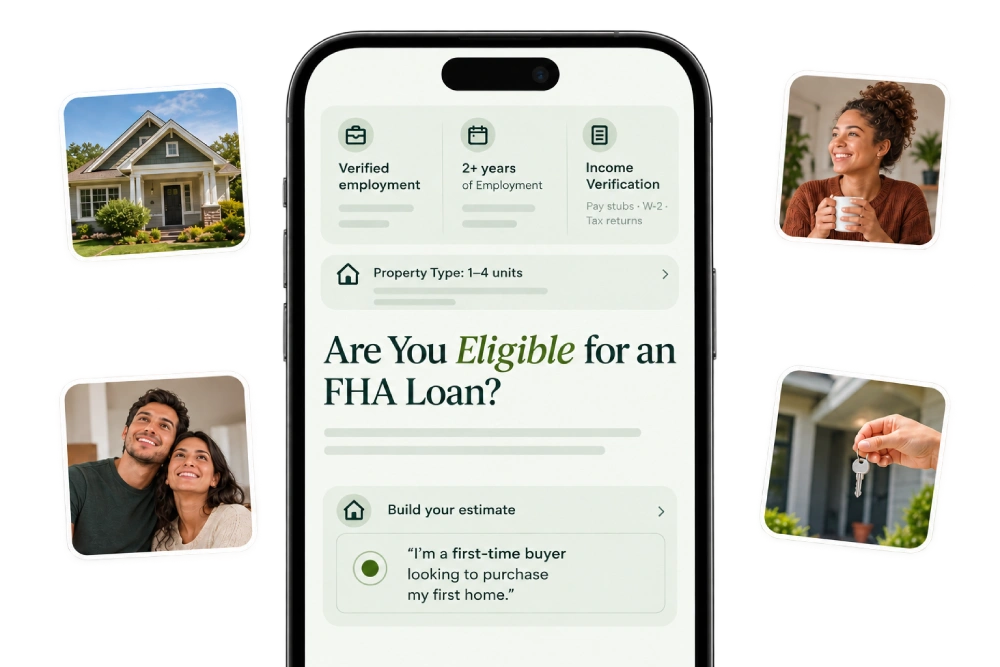
What Homeowners Say About Working With ACM
How Down Payment Assistance Works With ACM
From your first conversation to closing in 5 steps.
01
01
Tell Us About Your Plans
Complete the short eligibility form with your preferred location, estimated credit range and homebuying timeline.
02
02
Review Your Qualifications
A licensed loan officer reviews your income, credit, debts and estimated purchase budget against FHA and assistance guidelines.
03
03
Compare Your Options
We explain which assistance structures may be available, what your estimated payment could look like and how much cash you may still need for closing.
04
04
Get Pre-Approved
Once your documents are reviewed, you can start shopping with a clearer picture of your budget and the assistance available to you.
05
05
Close With the Assistance
The first mortgage and the down payment assistance are completed together as part of your home purchase.
Down Payment Assistance Program Comparison
See which DPA option fits your situation best.
| Feature | In-House Forgivable | In-House Repayable | TSAHC Options |
|---|---|---|---|
| DPA amount | 3.5% | 3.5% or 5% | 2% to 5% |
| Interest rate | 0% | First mortgage rate + 2% | 0% |
| Term | 30 years | 10 years, amortized | No lien on the grant; 3 years on the forgivable second |
| Monthly payment | None | Required | None |
| Forgiveness | After 36 on-time payments, at borrower request | Not forgivable; repayment required | Grant is never repaid; the forgivable second clears after 3 years |
| First-time buyer required? | No | No | No |
| Best for | Borrowers who want simplicity and plan to stay | Borrowers who need the most assistance and can afford a second mortgage payment | Eligible Texas buyers, including teachers, first responders and veterans |
| Texas DPA guide | FHA loans | How much cash you need |
Assistance programs, terms and availability vary by program and lender. Texas programs have income and purchase price limits. Each assistance program has its own lender requirements.
Talk to a Mortgage Expert About Your Down Payment
Get answers on your credit, down payment and assistance options from a licensed loan officer before you apply.
Talk to a Mortgage ExpertWhy Shop Down Payment Assistance With ACM
Assistance rules vary by program and lender. Comparing many lenders changes what you can qualify for and what you pay.
01 Rates
We Find Your Best Rate
Your loan officer compares DPA-eligible rates from 100+ lenders and brings you the strongest offer your file qualifies for.
02 Speed
Pre-Approved in One Day
Know your budget and your assistance options tomorrow.
03 Underwriting
In-House Underwriting
Your file stays with our team from submission to clear to close.
04 Reviews
500+ Five-Star Reviews
Texas buyers rate us five stars.
Down Payment Assistance: Your Questions Answered
Get clear answers on repayable and forgivable second liens, mortgage insurance and self-employed income.
How is a repayable second lien different from a forgivable one?
A repayable second lien is paid back over time with interest, and the payment counts in your debt-to-income ratio.
A forgivable second lien carries no monthly payment and is forgiven when you meet its terms. If you sell or refinance before then, the balance generally becomes due.
Does the assistance change my mortgage insurance?
Your FHA first mortgage carries standard FHA mortgage insurance. Your loan officer shows the full monthly payment, including insurance, in your quote.
Can I use down payment assistance with self-employed income?
Yes, when the first mortgage program accepts how you document your income. Your loan officer matches your documents to an eligible program.
Next step
Get Your Free Rate Quote
- Compare DPA-eligible rates from 100+ lenders
- Takes about 2 minutes
- No obligation
Meet Your Loan Officers
Every ACM borrower works with one licensed loan officer from application to closing.

Lance Kotal
Loan Originator
Lance Kotal
NMLS: 308707Lance has been a loan officer in Austin since 2001. A UT Austin economics graduate who helped his father build houses, he brings hands-on knowledge of homes to the financing conversation.
View Profile
Clint Brinkoeter
Loan Officer
Clint Brinkoeter
NMLS: 2592637Clint has more than a decade of experience in mortgage origination. A Texas State finance graduate, he's known for his market knowledge and close community ties.
View Profile
Adrienne Sanchez
Loan Officer
Adrienne Sanchez
NMLS: 1213046Adrienne entered the mortgage industry in 1994, led operations at a mortgage company and joined ACM in 2009. She brings three decades of lending experience to every file.
View Profile
Tom Oltmann
Loan Officer
Tom Oltmann
NMLS: 308768Tom has originated loans at ACM since 2008, after more than a decade managing retail stores for AT&T. He works with first-time buyers and investors and keeps clients informed at each step.
View Profile
Charlie Cooper
President
Charlie Cooper
NMLS: 326203Charlie leads Austin Capital Mortgage and brings a long-term view of the lending business to every file. A University of Houston finance graduate, he's known for getting to the right answer quickly.
View ProfileGet Your Free Rate Quote
Compare rates from 100+ lenders in 2 minutes, or talk with a loan officer today.
Down payment assistance questions? We’ve got answers.
Clear answers on how to apply, who qualifies, how much you can get and what to expect before closing.
More questions? See our Mortgage FAQs.
Still have a question?
Speak with a local mortgage expert and get answers tailored to your situation.
Does ACM offer down payment assistance in Texas?
Yes. Your loan officer can review FHA second-lien assistance and Texas state assistance for your purchase. Availability depends on your credit, income, property and county.
How do I apply for down payment assistance?
Start with a free rate quote or call us. We pre-approve you in one day, select the program that fits your file, and handle the second-lien paperwork with your mortgage.
How do I qualify for down payment assistance?
You need to meet your program’s minimum credit score, occupy the home as your primary residence, complete homebuyer education, and fit any income limit. See the requirements above for the scores by program.
Is down payment assistance a grant or a loan?
It depends on the program. The FHA second-lien options are loans, either repayable or forgivable. Texas state assistance includes a grant option and a forgivable second lien.
Can I use down payment assistance if I am not a first-time buyer?
Often yes. The FHA second-lien options and the Texas non-bond DPA do not require first-time buyer status. Your loan officer will confirm the rules for your option.
Does down payment assistance work with an FHA loan?
Yes. Assistance is available with FHA and works as a second loan alongside your FHA first mortgage. Texas programs also work with VA, USDA and HFA conventional.
How much assistance can I get?
FHA second-lien options provide 3.5% or 5% of the lower of the price or appraised value. Texas state programs provide 2% to 5% of the loan amount.
How long does closing take with down payment assistance?
You can close in 10 to 21 days from contract. Your appraisal and title timing can shift that, and your loan officer keeps you posted.
Keep learning about down payment assistance.
Guides on down payment assistance, closing costs and the home buying process.